

 融資信息
 專題
 鏈上生態
 詞條
 播客
 活動
 OPRR


SK Hynix Can This Round Double Again?

TL;DR
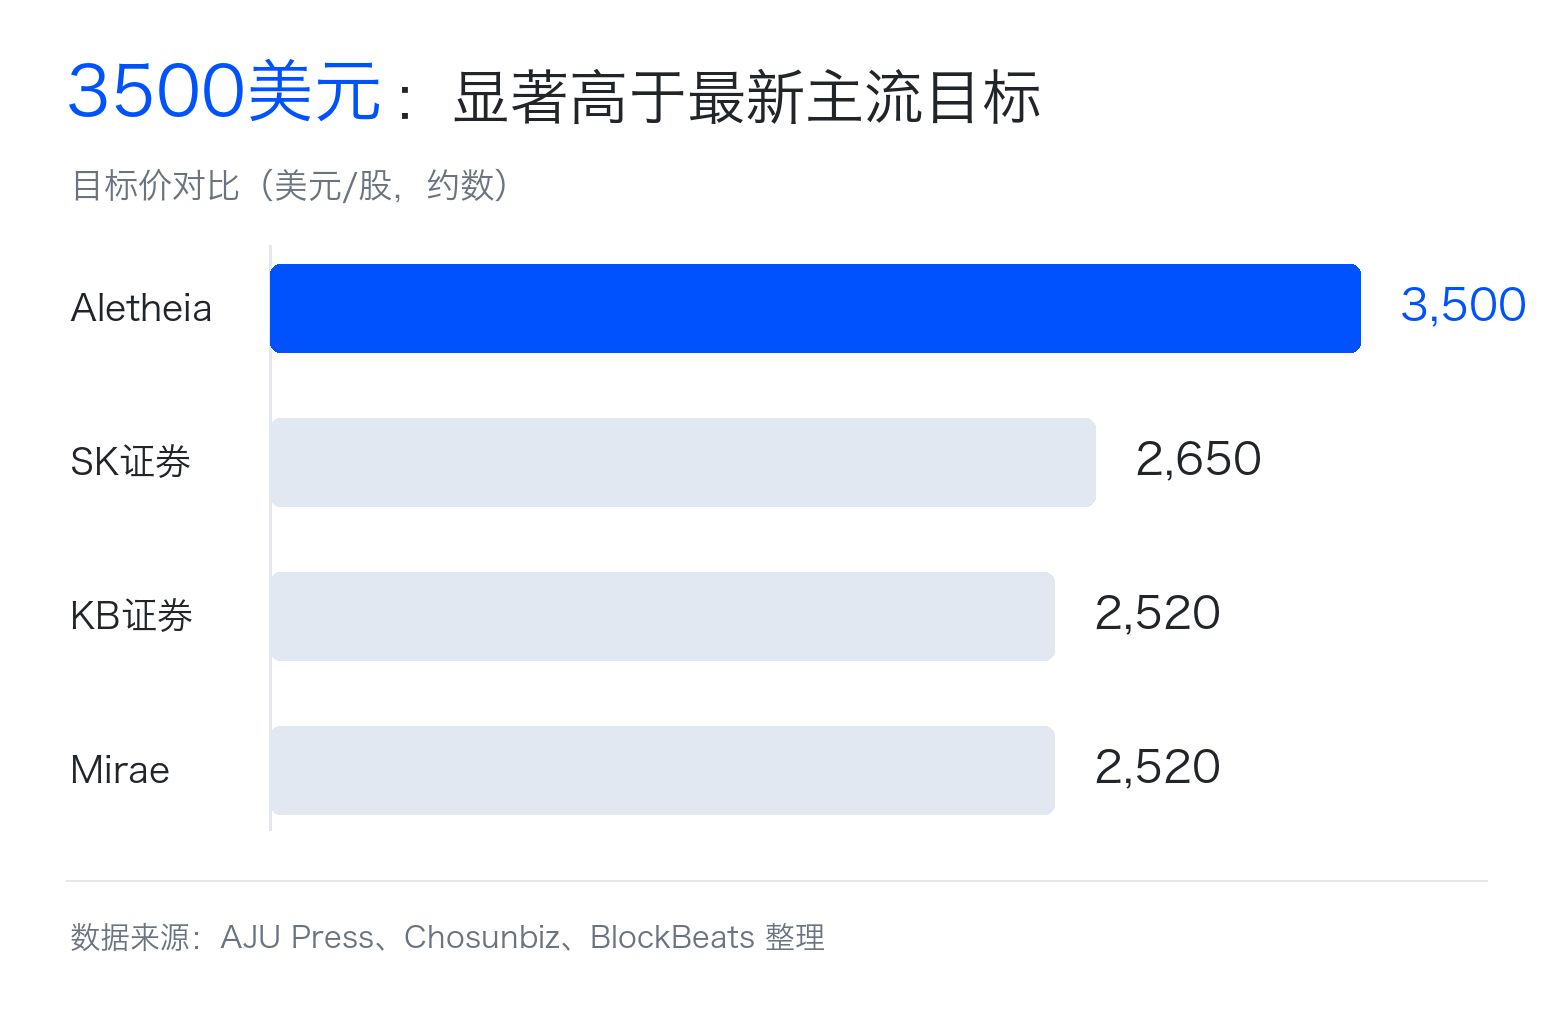
· Aletheia Capital has raised its target price for SK Hynix to around $3,500, significantly higher than the target range of around $2,000 to $2,520 set by several mainstream institutions.
· At the core of this pricing divergence is whether the market is willing to believe that HBM shortage, DRAM price increases, and improved free cash flow can continue until 2027.
· Related entities: SK Hynix, Samsung Electronics, Micron, NVIDIA supply chain.
In a report released today, Aletheia Capital raised its target price for SK Hynix to around $3,500, positioning it well above the target range of mainstream institutions.
Aletheia Capital is an independent research and investment advisory firm headquartered in Hong Kong, serving institutional investors and covering sectors such as Asian technology hardware; in contrast, the publicly reported target price for SK Securities is around $2,000, and for Mirae Asset and KB Securities, around $2,520.
What truly stands out about the $3,500 target price is not just its optimism compared to mainstream institutions, but the market is being asked to believe in three simultaneous events: the ongoing shortage of HBM (high-speed memory for AI chips), continued price increases in mainstream DRAM, and AI server demand sustaining the storage boom along with free cash flow until 2027.
The market has already acknowledged that SK Hynix should be revalued, but the disagreement lies in how far this revaluation should go; most mainstream institutions still apply a cyclical industry discount, while $3,500 extends into an optimistic tail scenario beyond the revaluation.
Disagreement Centers on 2027 Profit Base
The $3,500 price target is most easily misinterpreted as a simple valuation issue: as long as SK Hynix is given a 10 times multiple of 2027 earnings or free cash flow, the stock price can continue to rise. The challenge lies not in the multiple itself, but in how much money the company can actually earn and retain in cash by 2027.
Profitability for storage companies fluctuates greatly. During upswings, prices rise, inventory is depleted, and profit margins expand rapidly. During downturns, new capacity is released, customers reduce orders, prices fall back, and profits may quickly reverse. This is also why the market has long given storage companies lower valuation multiples.
即便 SK 海力士當前盈利強勁,公開報導提到的 12 個月遠期市盈率仍在個位數區間。市場不是看不見 AI,而是在擔心這輪上漲最終仍會按周期高點定價。
Aletheia 流傳出的激進目標價,挑戰的是這種周期折價。按公開轉述,它押注 AI 硬件需求持續推高 HBM 和 DRAM 價格,SK 海力士 2027 年自由現金流顯著超出當前多數預期,所以可以用更高基數重新定價。
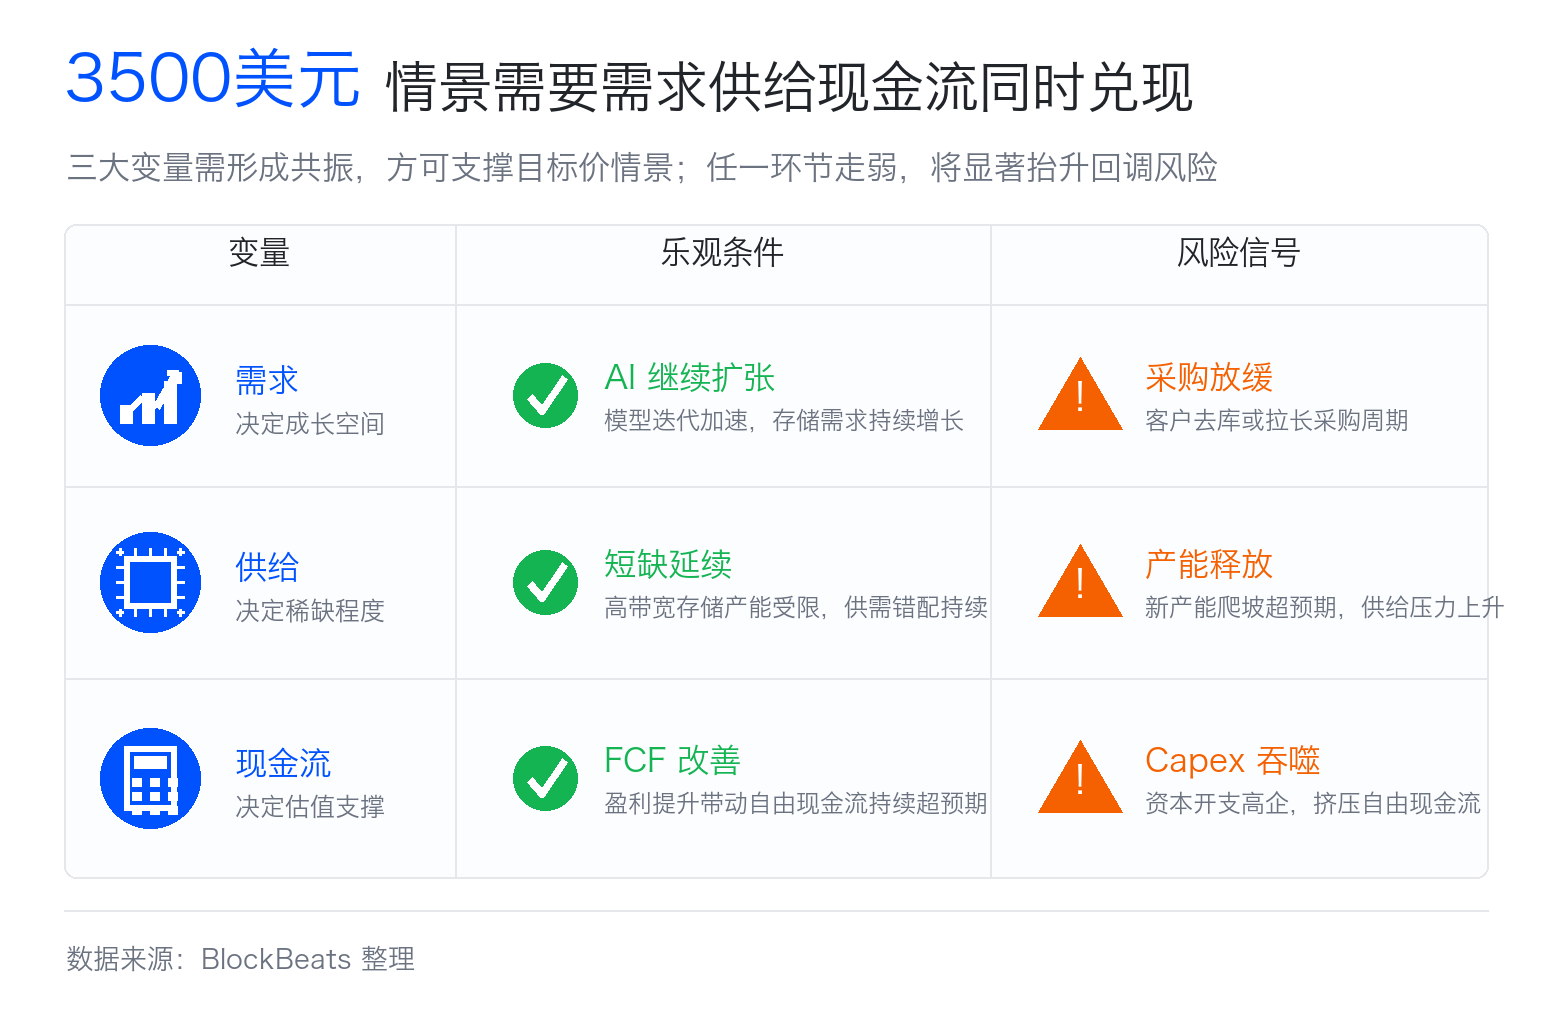
問題在於,3,500 美元要求多個變量同時站在有利一側:HBM 價格持續強,普通 DRAM 價格不被新產能打下來,SK 海力士維持領先份額,資本開支沒有吞掉太多現金,市場還願意給周期股一個不低的倍數。任何一環低於預期,目標價就會從結構性重估變成高景氣外推。
HBM 把短缺傳導到普通內存
HBM 能改變 SK 海力士定價邏輯,是因為它不是普通記憶體的小升級,而是 AI 加速卡旁邊的核心組件。AI 晶片算得再快,如果數據餵不進去,整體性能也會被卡住。HBM 的作用,就是給 GPU 或 AI 加速器提供更高帶寬的數據通道。
普通投資者可以把它理解成:GPU 是發動機,HBM 是高速供油系統。發動機越強,對供油系統要求越高。過去市場交易 AI 硬件,最先看英偉達 GPU。現在市場越來越意識到,GPU 能不能出貨、AI 伺服器能不能堆起來,也取決於 HBM 供給。
HBM 的供給也不是把普通 DRAM 產線稍微改一下就能立刻放量。它需要更複雜的堆疊、封裝和客戶認證,還會消耗更多晶圓面積與先進封裝資源。生產同等容量的 HBM,通常會佔用比普通 DRAM 更多的產能資源。
這會把影響擴散到普通內存。廠商把更多資源轉去做 HBM,普通伺服器、PC、手機等領域使用的 DRAM 供給會變緊,DRAM 平均售價也可能被推高。
這正是約 3,500 美元目標價能講通的核心機制。如果 HBM 只是一個增長很快的小產品,它只能提升 SK 海力士的一部分收入。如果 HBM 同時擠壓普通 DRAM 供給、抬高整個內存價格曲線,它就會成為全公司利潤率和現金流的放大器。
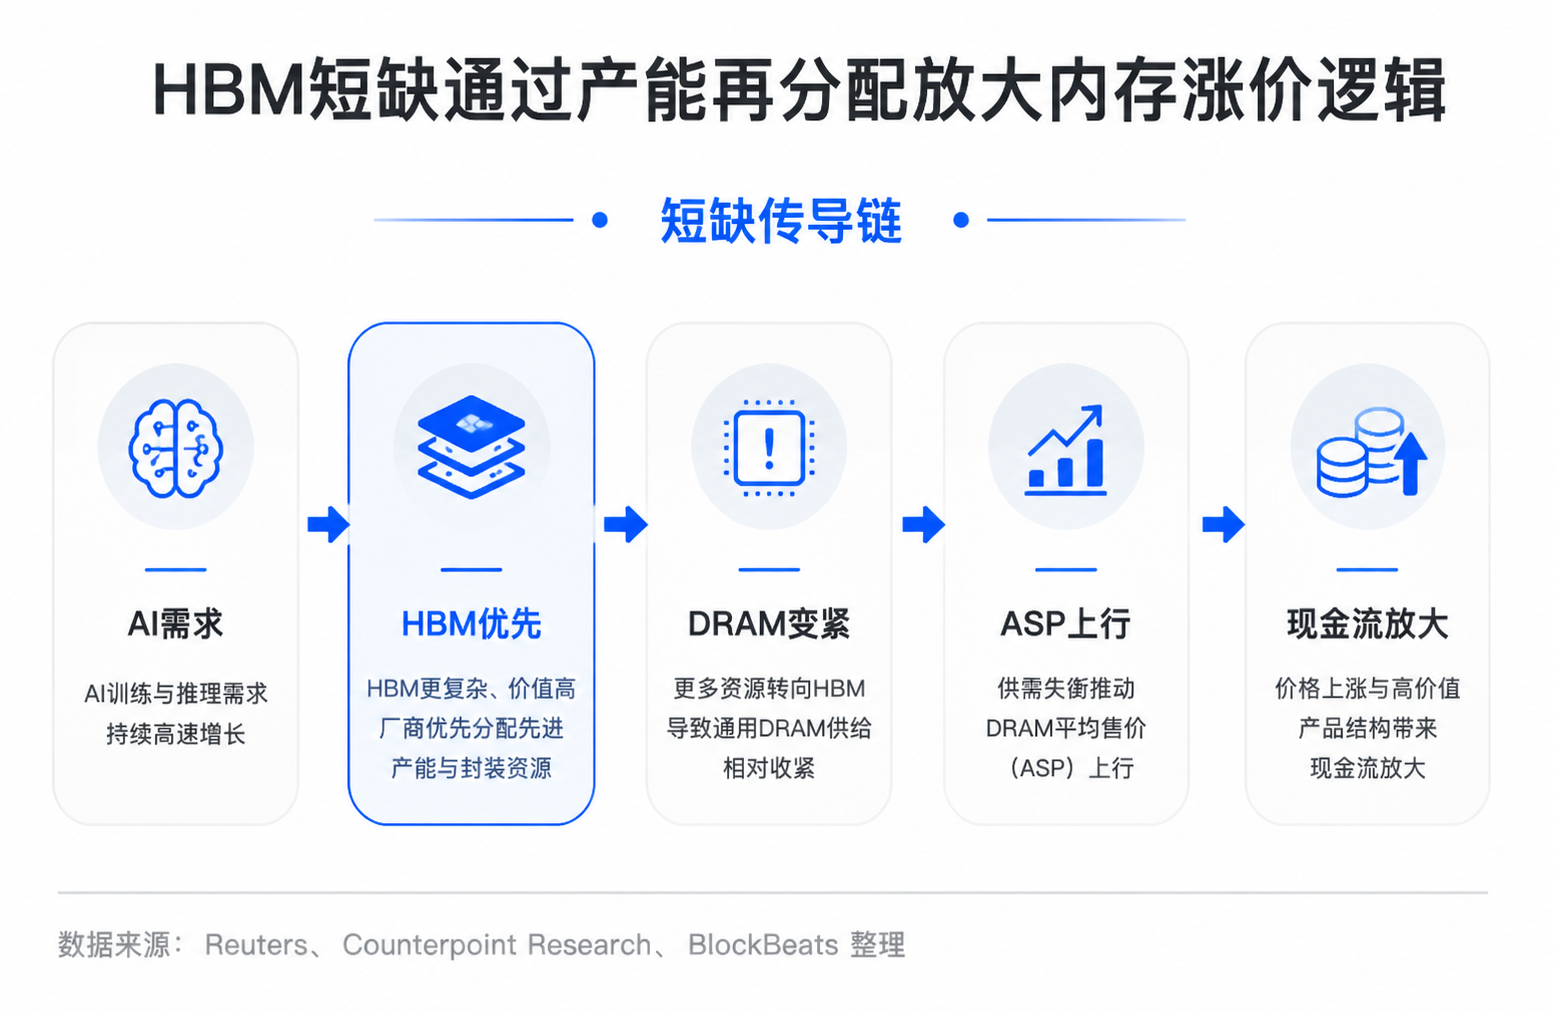
但 HBM 缺乏可能只會延長周期,而非終結周期。三星和美光都在追趕,SK 海力士也將擴大產能,新晶圓廠和封裝能力最終將反映在供應端。爭議的核心不在於缺乏是否存在,而在於缺乏將持續多久,價格還能強勁多久。
SK 海力士吞下最直接的供應鏈溢價
SK 海力士成為這輪重新評估的核心,不僅因為它是存儲公司,還因為它在 HBM 領域遙遙領先。據路透社引述 Counterpoint 數據,2026 年第一季度,SK 海力士在全球 HBM 市佔約為58%,而三星和美光各約21%。路透社也曾稱其為 NVIDIA HBM 供應鏈中的重要供應商。
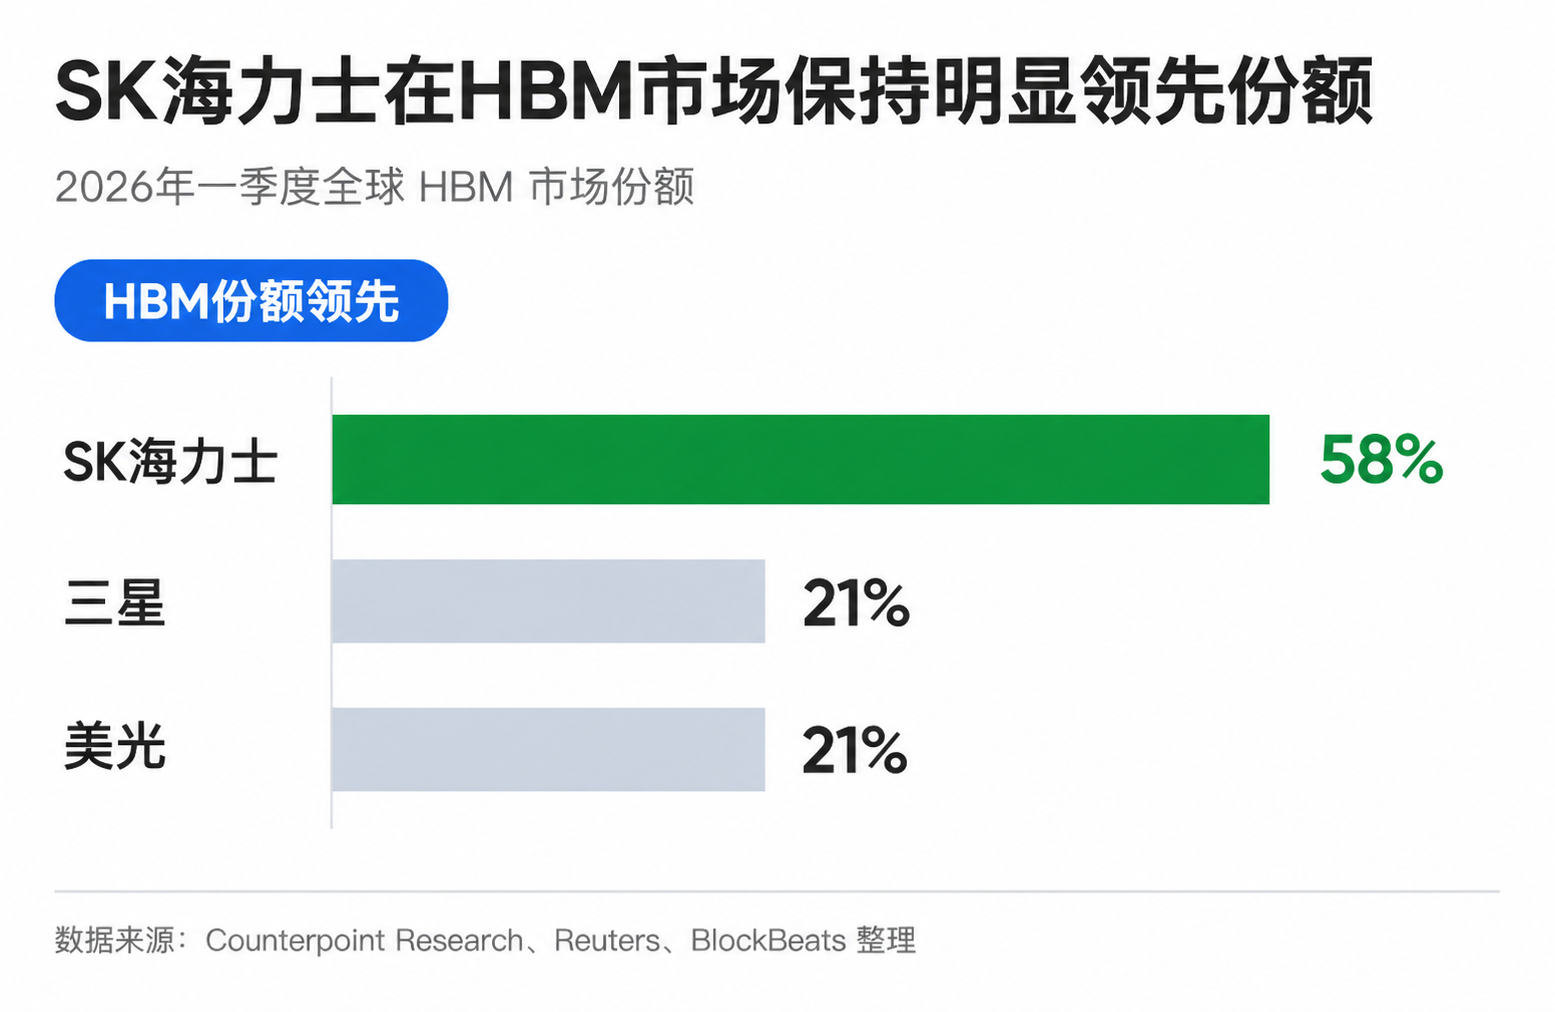
在半導體供應鏈中,這種領先地位非常珍貴。AI 芯片製造商選擇 HBM,不僅僅是看價格,還要考慮性能、良率、穩定性和認證進度。越早通過客戶認證,越容易進入下一代產品合作窗口。越早鎖定訂單,越容易在產能規劃和價格談判中佔據主動。
這也是2026年供需情況受到關注的原因。根據路透社2025年的報導,SK 海力士已經與重要客戶完成了關於 2026 年 HBM 供應的討論。許多行業報導也指出,HBM 短缺可能持續到 2027 年。對於投資者來說,2026 年的業績至少不完全依靠故事支撐。
SK 海力士的受益不僅限於 HBM 收入本身。由於 HBM 占用了更多產能,普通 DRAM 供應受到擠壓,傳統內存業務也可能從價格上涨中受益。AI 需求首先通過 HBM 進入財報,再通過產能再分配影響整個 DRAM 價格。
這解釋了為什麼機構的目標價不斷上調。即使不接受 3,500 美元這種極端情況,約 2,000 至 2,520 美元的目標價也表明,主流機構已在重新評估 SK 海力士 2026 至 2027 年利潤彈性。差異在於,它們多數仍保留了週期性行業應有的折扣,沒有將 2027 年後的短缺直接推演為新常態。
一倍漲幅要等三件事兌現
Aletheia 流傳出的 3,500 美元目標價,本質上押注需求持續強勁、供應持續緊張、現金流繼續超預期。過去兩年,雲端供應商和 AI 公司大規模採購 GPU,帶動 HBM 需求爆發;接下來市場要關注的是,推理、企業 AI 和定制 ASIC 能否繼續擴大內存消耗,讓需求不僅停留在訓練集群。
供應端同樣不能太快鬆動。2026 年的緊張相對容易理解,因為產能、封裝和客戶認證都有滯後;到 2027 年,三星、SK 海力士、美光的新產能與新產品都會逐步進入市場。若新增供應快於預期,HBM 價格漲幅可能收窄,普通 DRAM 也會重新面對壓力。
最終還是要落到現金流。存儲行業景氣上行時,公司往往會增加資本支出,擴產、升級製程、佈局先進封裝。利潤增長不一定全部留在帳上,如果 SK 海力士需要用更大投資維持領先,3,500 美元的目標價依賴的自由現金流基數就會被削弱。
因此,這個目標價更適合被看作樂觀情景,而不是已經驗證的市場共識。2027 年才是真正的觀察窗口:只要 HBM 價格、DRAM 均價、供應節奏和自由現金流持續站在有利一側,市場會相信 AI 正在抬高記憶體行業的利潤中樞;如果價格先鬆、供應先到、現金流被資本支出吞掉,約 3,500 美元就會從重評錨變成情緒高點。
歡迎加入律動 BlockBeats 官方社群:
Telegram 訂閱群:https://t.me/theblockbeats
Telegram 交流群:https://t.me/BlockBeats_App
Twitter 官方帳號:https://twitter.com/BlockBeatsAsia







